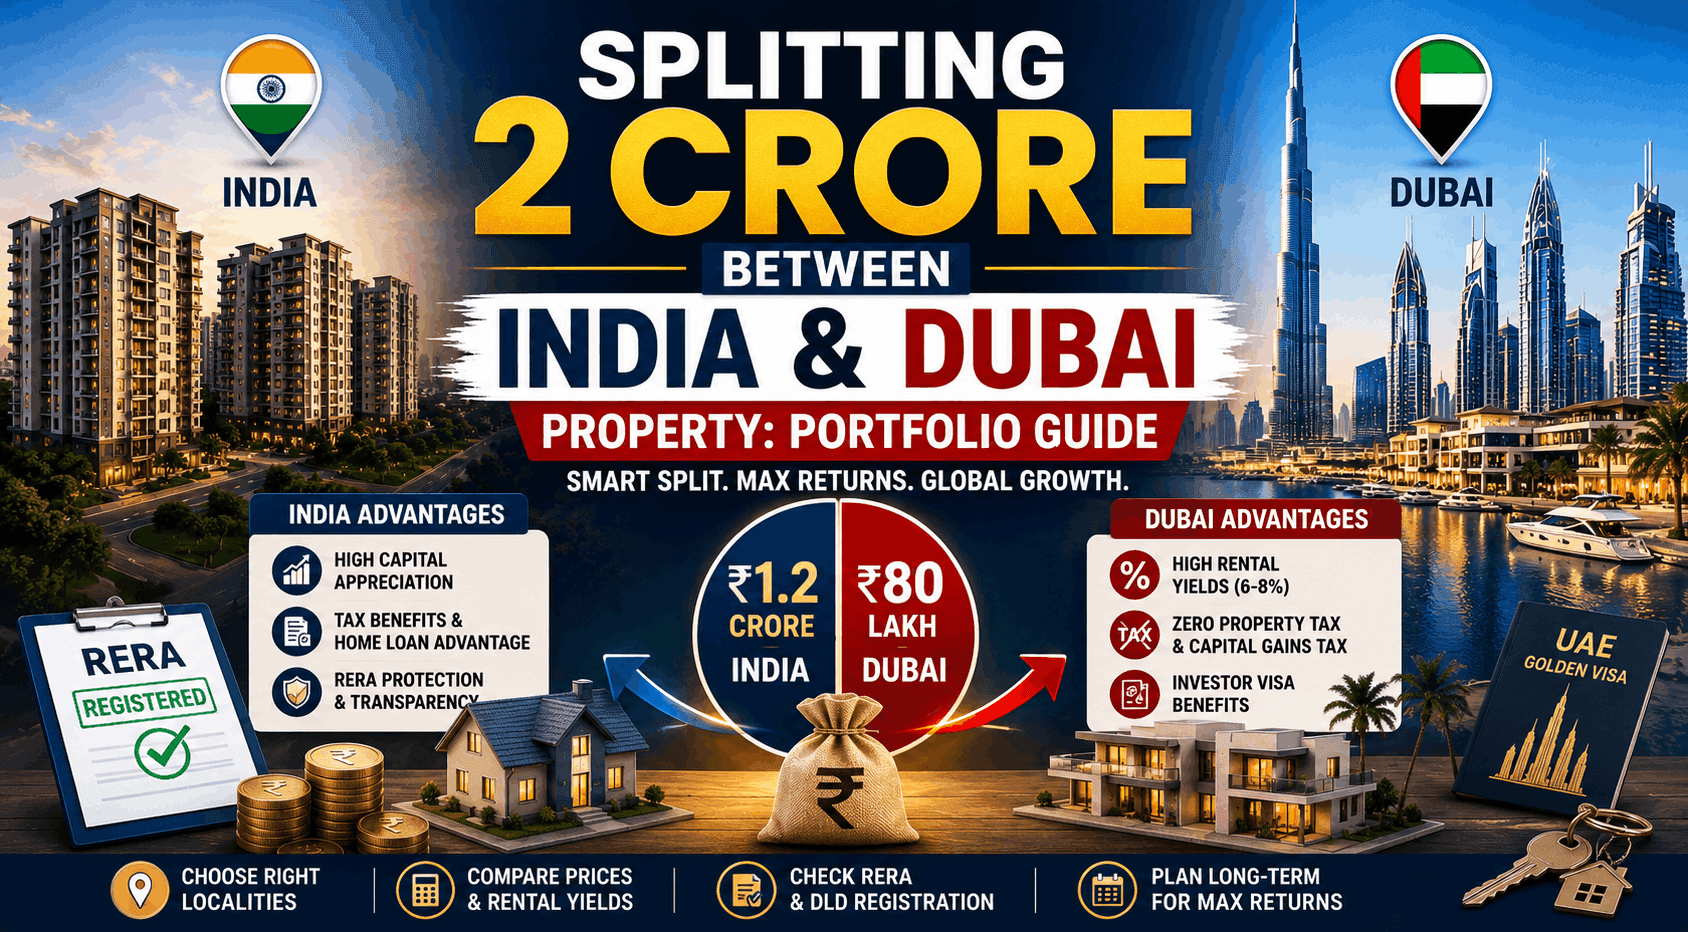

Are you an NRI or a Gujarat-based investor juggling the idea of refinancing your home loan? The year 2026 brings a fresh wave of opportunities, but the decision is no longer simple. You have two compelling paths: a Loan Refinance 2026: Balance Transfer in India vs Dubai Mortgage. Each has its own tax quirks, currency risks, and local market advantages.
I have seen countless buyers in Ahmedabad’s SG Highway and Surat’s Vesu struggle with this choice. The truth is, your property’s location, your income source, and your long-term goals will tilt the scale. Let me break it down for you — no jargon, just practical advice.
Why 2026 Is a Pivotal Year for Loan Refinance
Interest rates are shifting globally. In India, the RBI has hinted at a marginal rate cut, while Dubai’s central bank follows the US Federal Reserve. For a buyer in Gandhinagar’s GIFT City, a 0.25% drop on a Rs 50 lakh loan translates to Rs 1.2 lakh in savings over five years. But here is the catch: Dubai’s mortgage rates are often fixed for the first three years, while Indian banks prefer floating rates.
The Indian Balance Transfer Advantage
A balance transfer in India is straightforward. You move your outstanding loan from Bank A to Bank B for lower EMI or better terms. In Gujarat, I have seen NRIs from Rajkot’s Kalawad Road save up to 0.5% per annum by switching from SBI to HDFC.
- Processing fee: Typically 0.5% to 1% of the loan amount. For a Rs 40 lakh loan, that is Rs 20,000 to Rs 40,000.
- Documentation: Simple Aadhaar, PAN, income proof, and property papers.
- Tax benefit: Under Section 24(b), you can claim up to Rs 2 lakh on interest. Plus, Section 80C for principal repayment up to Rs 1.5 lakh.
But what does this mean for you? If your current loan has a high spread (say 9.5% p.a.), and a new lender offers 8.75%, the switch makes sense within 2-3 years. I personally recommend checking your loan’s prepayment penalty first — some older loans have a 2% charge.
Dubai Mortgage: The NRI’s Dilemma
Dubai’s real estate market is booming, especially in areas like Dubai Marina and Palm Jumeirah. But a mortgage there is a different beast. For a Gujarat-based NRI, the key challenges are currency fluctuation and documentation.
How Dubai Mortgages Work
- Interest rates: Usually 4% to 5% p.a. for fixed periods, then floating. Compare that to India’s 8.5% to 9.5% — looks cheaper, right?
- Loan-to-value ratio: Up to 75% for expats. So for a AED 1 million property (Rs 2.2 crore), you need a 25% down payment.
- Taxes: Zero property tax in Dubai, but no tax deduction on mortgage interest. That is a big trade-off.
Here is the thing: If you earn in dirhams and plan to return to India, the exchange rate risk is real. In 2023, the rupee depreciated 8% against the dirham. A Rs 5 lakh annual EMI could become Rs 5.4 lakh overnight.
Case Study: Amit from Ahmedabad
Take Amit, a software engineer in Dubai who bought a flat in Bopal, Ahmedabad, in 2020 for Rs 45 lakh. He had a loan from ICICI at 9.2%. In 2026, he is considering a balance transfer to Axis Bank at 8.6%. The savings? Rs 3,600 per month. But he also wants to buy a studio in Dubai’s JLT area. His dilemma: should he refinance his Indian loan or take a fresh Dubai mortgage?
What I advised him: First, refinance the Indian loan because the tax benefits are immediate. For the Dubai property, use a local bank like Emirates NBD, but only if he plans to stay in UAE for 5+ years. Short-term? Not worth the hassle.
Key Differences: India Balance Transfer vs Dubai Mortgage
| Aspect | India Balance Transfer | Dubai Mortgage |
|--------|------------------------|----------------|
| Interest Rate | 8.5% – 9.5% p.a. | 4% – 5% p.a. |
| Tax Benefits | Section 24(b) + 80C | None |
| Processing Fee | 0.5% – 1% | 1% – 2% |
| Currency Risk | Minimal | High (AED to INR) |
| Property Type | Residential only | Residential + Commercial |
The reality is: If your property is in Gujarat — say a 2BHK in Surat’s Adajan worth Rs 60 lakh — a balance transfer is a no-brainer. But if you are buying a villa in Dubai’s Arabian Ranches, a local mortgage makes sense despite the lack of tax breaks.
Practical Steps for Loan Refinance in 2026
Here is what I tell my clients in Vadodara’s Alkapuri and Rajkot’s 150 Feet Ring Road:
Step 1: Calculate Your Break-Even Point
Use this formula: (Processing fee + Prepayment penalty) / Monthly savings = Months to break-even. If it is under 18 months, go for it.
Step 2: Check RERA Compliance
For Indian properties, ensure the project is RERA registered. In Gujarat, RERA has made balance transfers smoother — lenders now verify project status online. Do not skip this step.
Step 3: Compare Total Cost
Don’t just look at the interest rate. Factor in processing fees, legal charges, and valuation fees. For a Dubai mortgage, add 1% for property valuation and 0.5% for mortgage registration.
Step 4: Negotiate Like a Pro
Banks in India are competitive. If you have a good CIBIL score (750+), ask for a waiver on the processing fee. In Dubai, request a lower fixed-rate period — 5 years instead of 3.
Quick Tips for NRIs and Gujarat Investors
- For a flat in Shela, Ahmedabad: Balance transfer to a smaller NBFC like DHFL may offer lower rates than SBI. But check their service quality.
- For a villa in Dubai’s Emirates Hills: Use a mortgage broker like Holo or SmartCrowd to get pre-approved before searching.
- Tax planning: In India, claim HRA if you live in a rented property while your loan property is vacant. Many buyers forget this.
- Currency hedge: If you earn in dirhams, consider a forward contract to lock in exchange rates for EMI payments.
Wondering where to start? Talk to a chartered accountant who understands both Indian and UAE tax laws. I have seen too many investors lose money on forex alone.
Conclusion: Your 2026 Action Plan
The choice between a Loan Refinance 2026: Balance Transfer in India vs Dubai Mortgage boils down to one question: where do you see yourself in five years? If you plan to retire in Gujarat, refinance your Indian loan and enjoy the tax benefits. If you are building a portfolio in Dubai, take a local mortgage but hedge your currency risk.
My personal recommendation: Do both — but only if your cash flow allows. Start with the balance transfer in India because it is low-hanging fruit. Then, use the savings to fund your Dubai down payment. That is what smart investors in GIFT City and Vesu are doing.
Ready to make a move? Compare three lenders today. Use an online EMI calculator, check your CIBIL score, and call at least two banks. The best deals are gone by March 2026.